America’s factory floors just logged their busiest month since 2021, and the signal was loud and clear.
Story Snapshot
- Manufacturing PMI rose to 55.5 in October, up from 54.5 in September
- Production Index jumped to 59.0, the strongest reading since November 2021
- Manufacturing expanded for the tenth straight month; production for the twelfth
- New orders held firm at 55.5, marking ten months of steady demand
Production Hit A Five-Year High, And That Matters
The Institute for Supply Management reported that factory production surged in October. Its Production Index rose to 59.0, the highest since late 2021, pointing to faster output on shop floors across many industries. The broader Manufacturing Purchasing Managers’ Index rose to 55.5, up for the second month in a row and signaling broader growth in activity. New orders also stayed strong at 55.5, which helps explain why production kept climbing.
These levels mark staying power, not a blip. Manufacturing expanded for ten straight months, while production increased for twelve. That kind of streak suggests managers see steady demand and have the parts and people to meet it. The October Production Index also rose 2.3 points from September’s 56.7, a clear month-to-month boost that pushed it to the top tier of post-pandemic readings.
What The Indexes Actually Tell Us
The Manufacturing Purchasing Managers’ Index is a diffusion survey. Readings above 50 mean more firms report growth than decline. They do not mean output rose by 55.5 percent. The Production Index tracks the share saying production rose. Historically, a reading above roughly 52 lines up with growth in the Federal Reserve’s industrial production series. The clean takeaway: more factories saw gains in October, and the gains were broader and faster than in September.
Conservative common sense aligns with this reading: when new orders rise and production rises, the economy’s supply side is doing its job. That helps cool bottlenecks without government micromanagement. It also supports better-paying work in towns built on machining, plastics, chemicals, and equipment. A sturdy industrial base means stronger communities and less reliance on fragile foreign supply chains. These data point in that direction, even if they are a survey snapshot rather than a physical count.
Demand, Capacity, And The Shop-Floor Reality
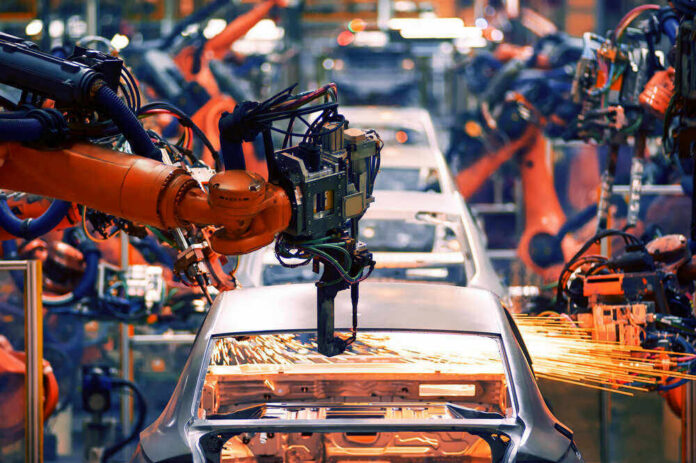
New orders at 55.5 show customers kept calling, and that keeps lines running. The Production Index at 59.0 shows managers found ways to build more with the labor and materials on hand. That often comes from overtime, more shifts, on-time parts, and smart scheduling. Coverage noted the October production surge was the strongest since 2021, matching reports that many plants worked through backlogs as parts became easier to get. That pattern fits what many firms faced after years of supply strain.
The US ISM manufacturing report released on November 2 put QQQ/USD on my watchlist this week. October’s PMI rose from 54.5 to 55.5, but the details tell a more nuanced story.
The first thing I noticed was production rising from 56.7 to 59, while new orders barely moved from 55.3… pic.twitter.com/u2dkfDBYWO
— lynhnexl (@MeoMeo14062017) November 3, 2026
The jobs picture looked mixed. The employment component edged down from 52.7 to 52.4, which still points to hiring, but at a slower pace. That can happen when factories lift output with process gains instead of headcount. For workers, that can mean steadier hours and more overtime before net new hiring. For owners, it means careful cost control while meeting orders. For both, a production index near 60 is a green light to keep plans rolling.
How To Read This For The Months Ahead
Two things drive durable expansions: steady demand and clean supply lines. October checked both boxes. Ten straight months of expanding orders and twelve months of rising production suggest momentum with depth. If that pattern holds into year-end, official industrial production should reflect it. One caution belongs here and only once: the Institute for Supply Management indexes are surveys, not a machine-by-machine count. Even so, markets and managers track them because they flag turns early and often map to real output over time.
Policy should aim at keeping this engine fueled. Keep energy reliable and affordable. Speed up permits for plants and grid upgrades. Cut red tape that slows equipment installs. Support skills training that gets teens and mid-career workers onto the floor fast. That playbook respects work, rewards merit, and anchors growth in real production, not paper shuffling. October’s report shows the payoff when we let builders build, and makers make.
Sources:
ismworld.org, morningstar.com, bloomberg.com, economics.td.com